
The test your strategy could not have been tuned for.
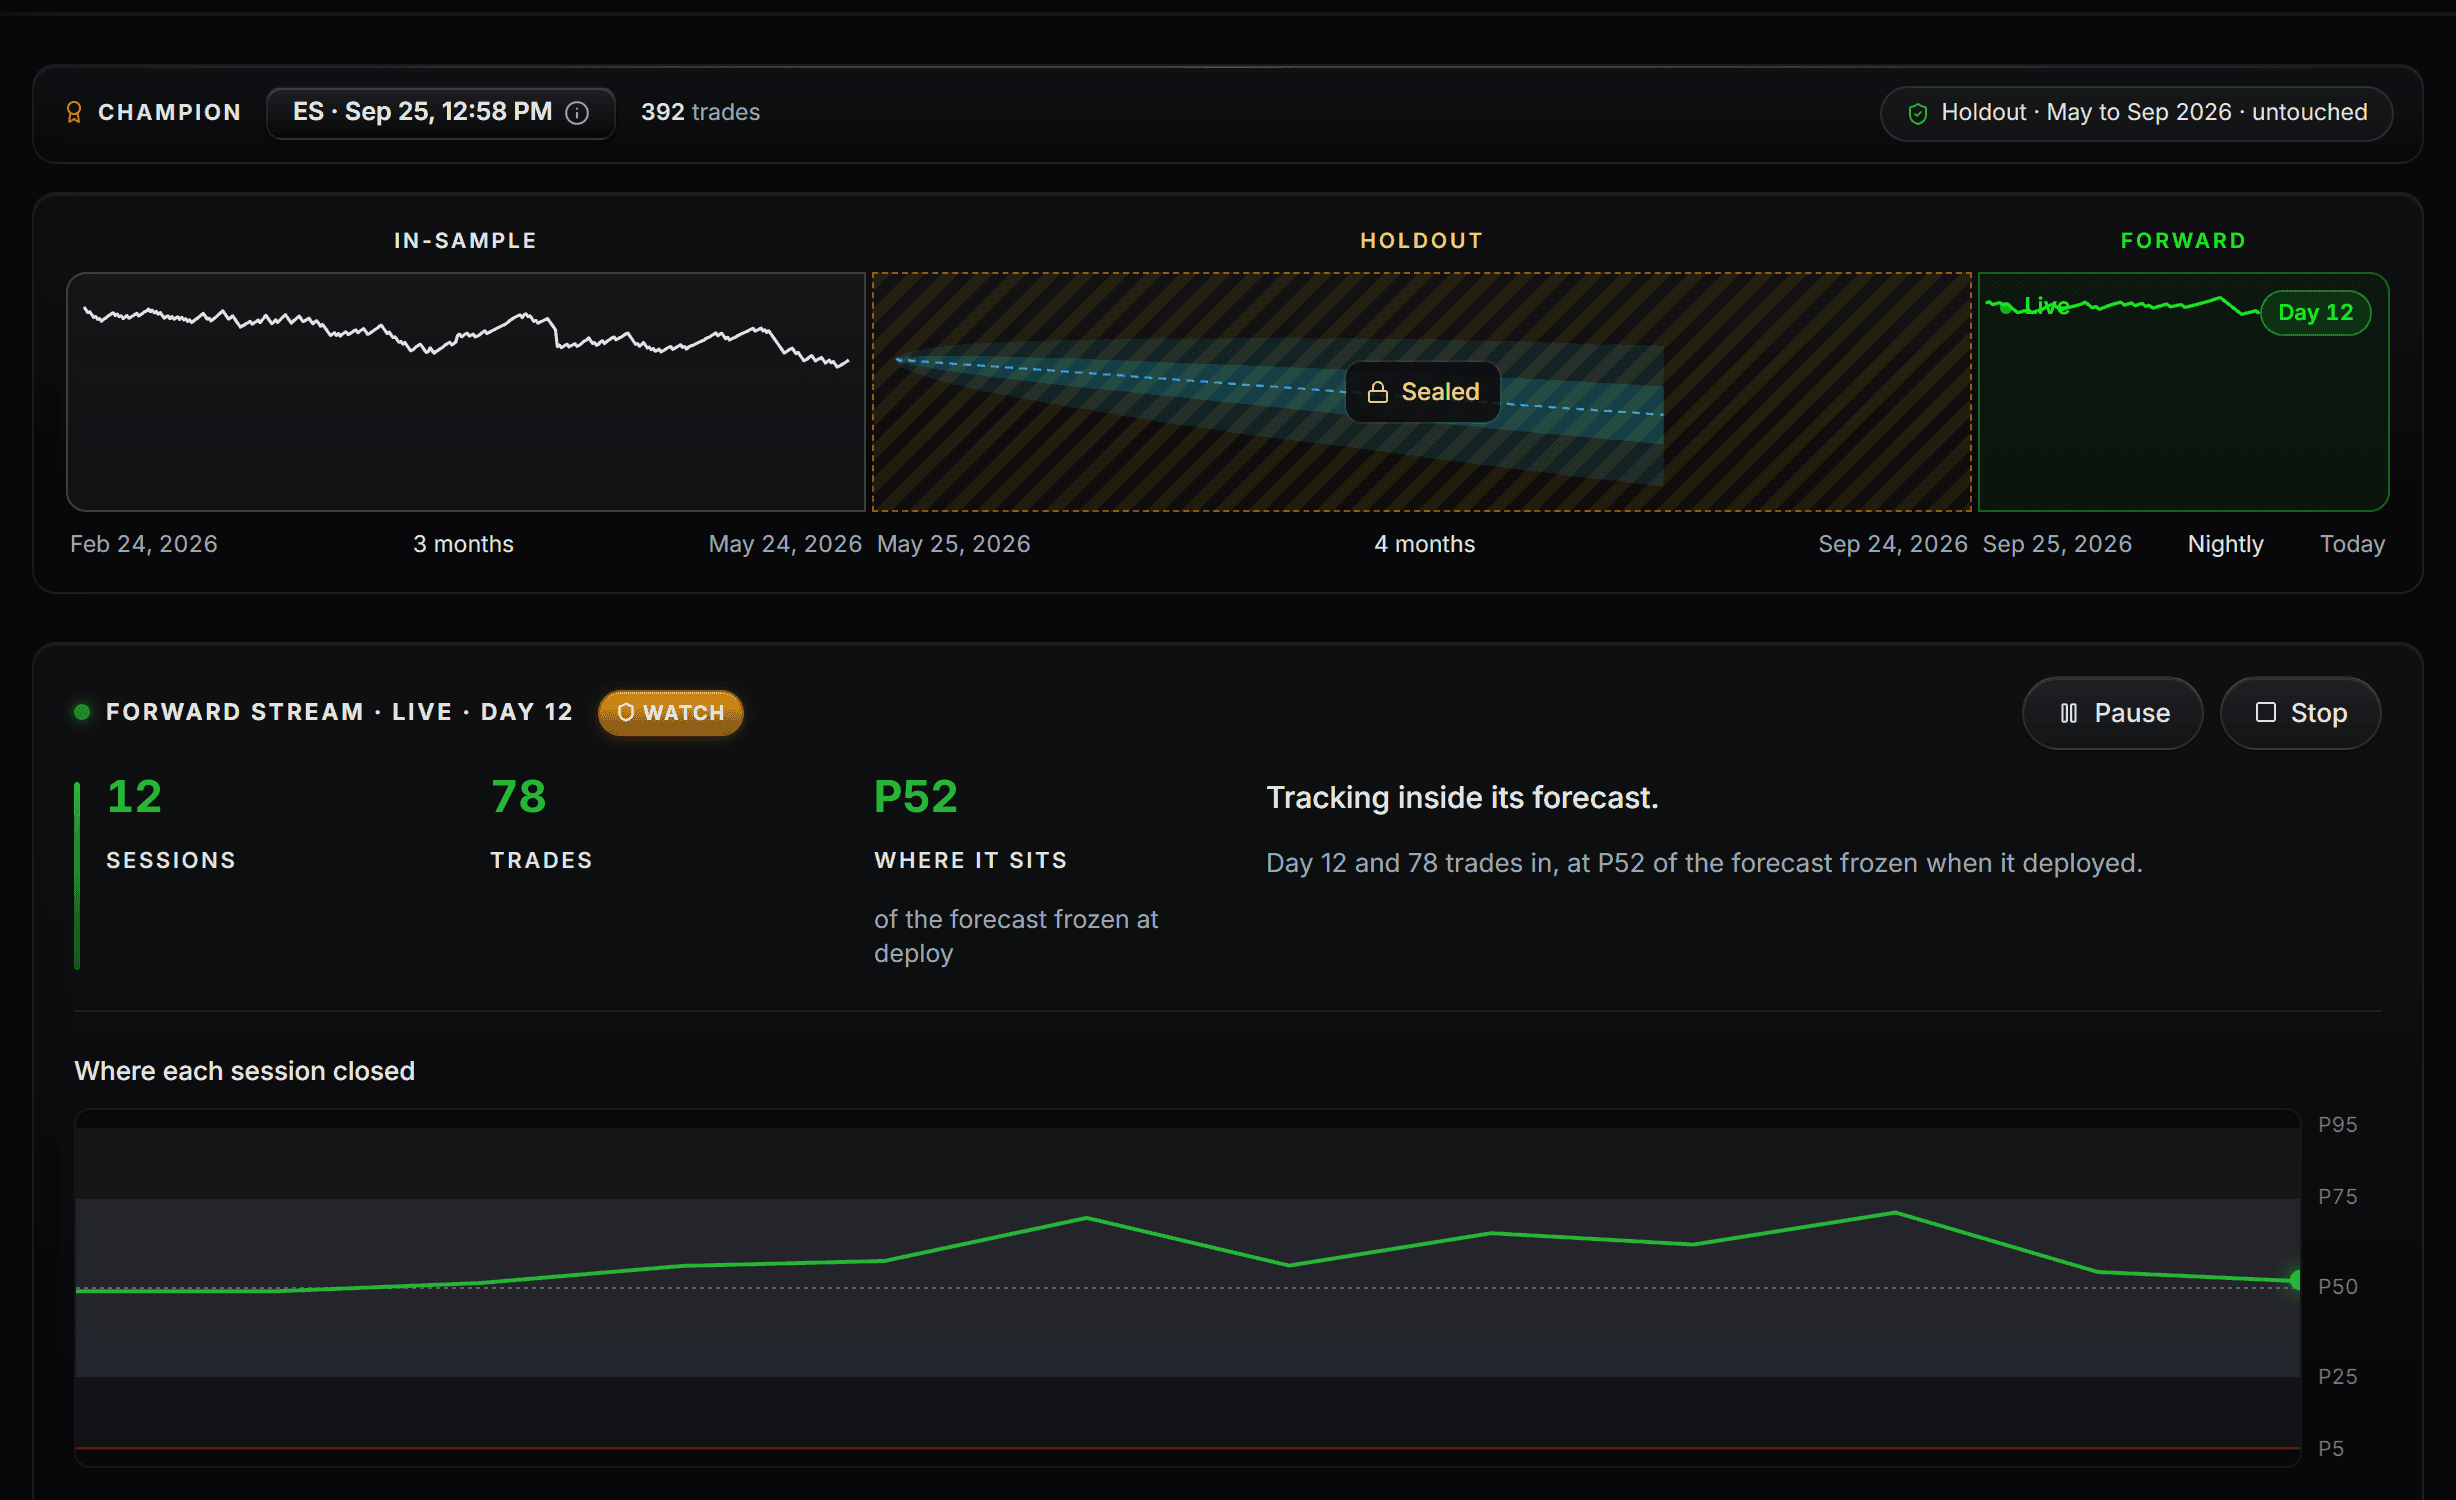
Forward testing runs your strategy on each new day of real market data and scores it against the range you saw before you deployed. Live execution is on our roadmap, and this page says exactly what that means.
Simulated results. They have inherent limitations. Read the full statementHide the statement
These results are based on simulated or hypothetical performance results that have certain inherent limitations. Unlike the results shown in an actual performance record, these results do not represent actual trading. Also, because these trades have not actually been executed, these results may have under-or over-compensated for the impact, if any, of certain market factors, such as lack of liquidity. Simulated or hypothetical trading programs in general are also subject to the fact that they are designed with the benefit of hindsight. No representation is being made that any account will or is likely to achieve profits or losses similar to these being shown.
Evidence from days that did not exist when you built it.
- Every new session, on real data
- After each session closes, your deployed strategy runs on that day's market data. Days that did not exist when you built it, so nothing was tuned on them.
- Scored against a range set in advance
- The Monte-Carlo range of outcomes is saved when you deploy. Each new day is scored against that saved range, never a fresh one drawn after the fact.
- Invalidation you can't argue with
- If the strategy keeps closing below the low end of its saved range, the forward test is marked invalidated, and your project's verdict says so.
- A holdout, spent once
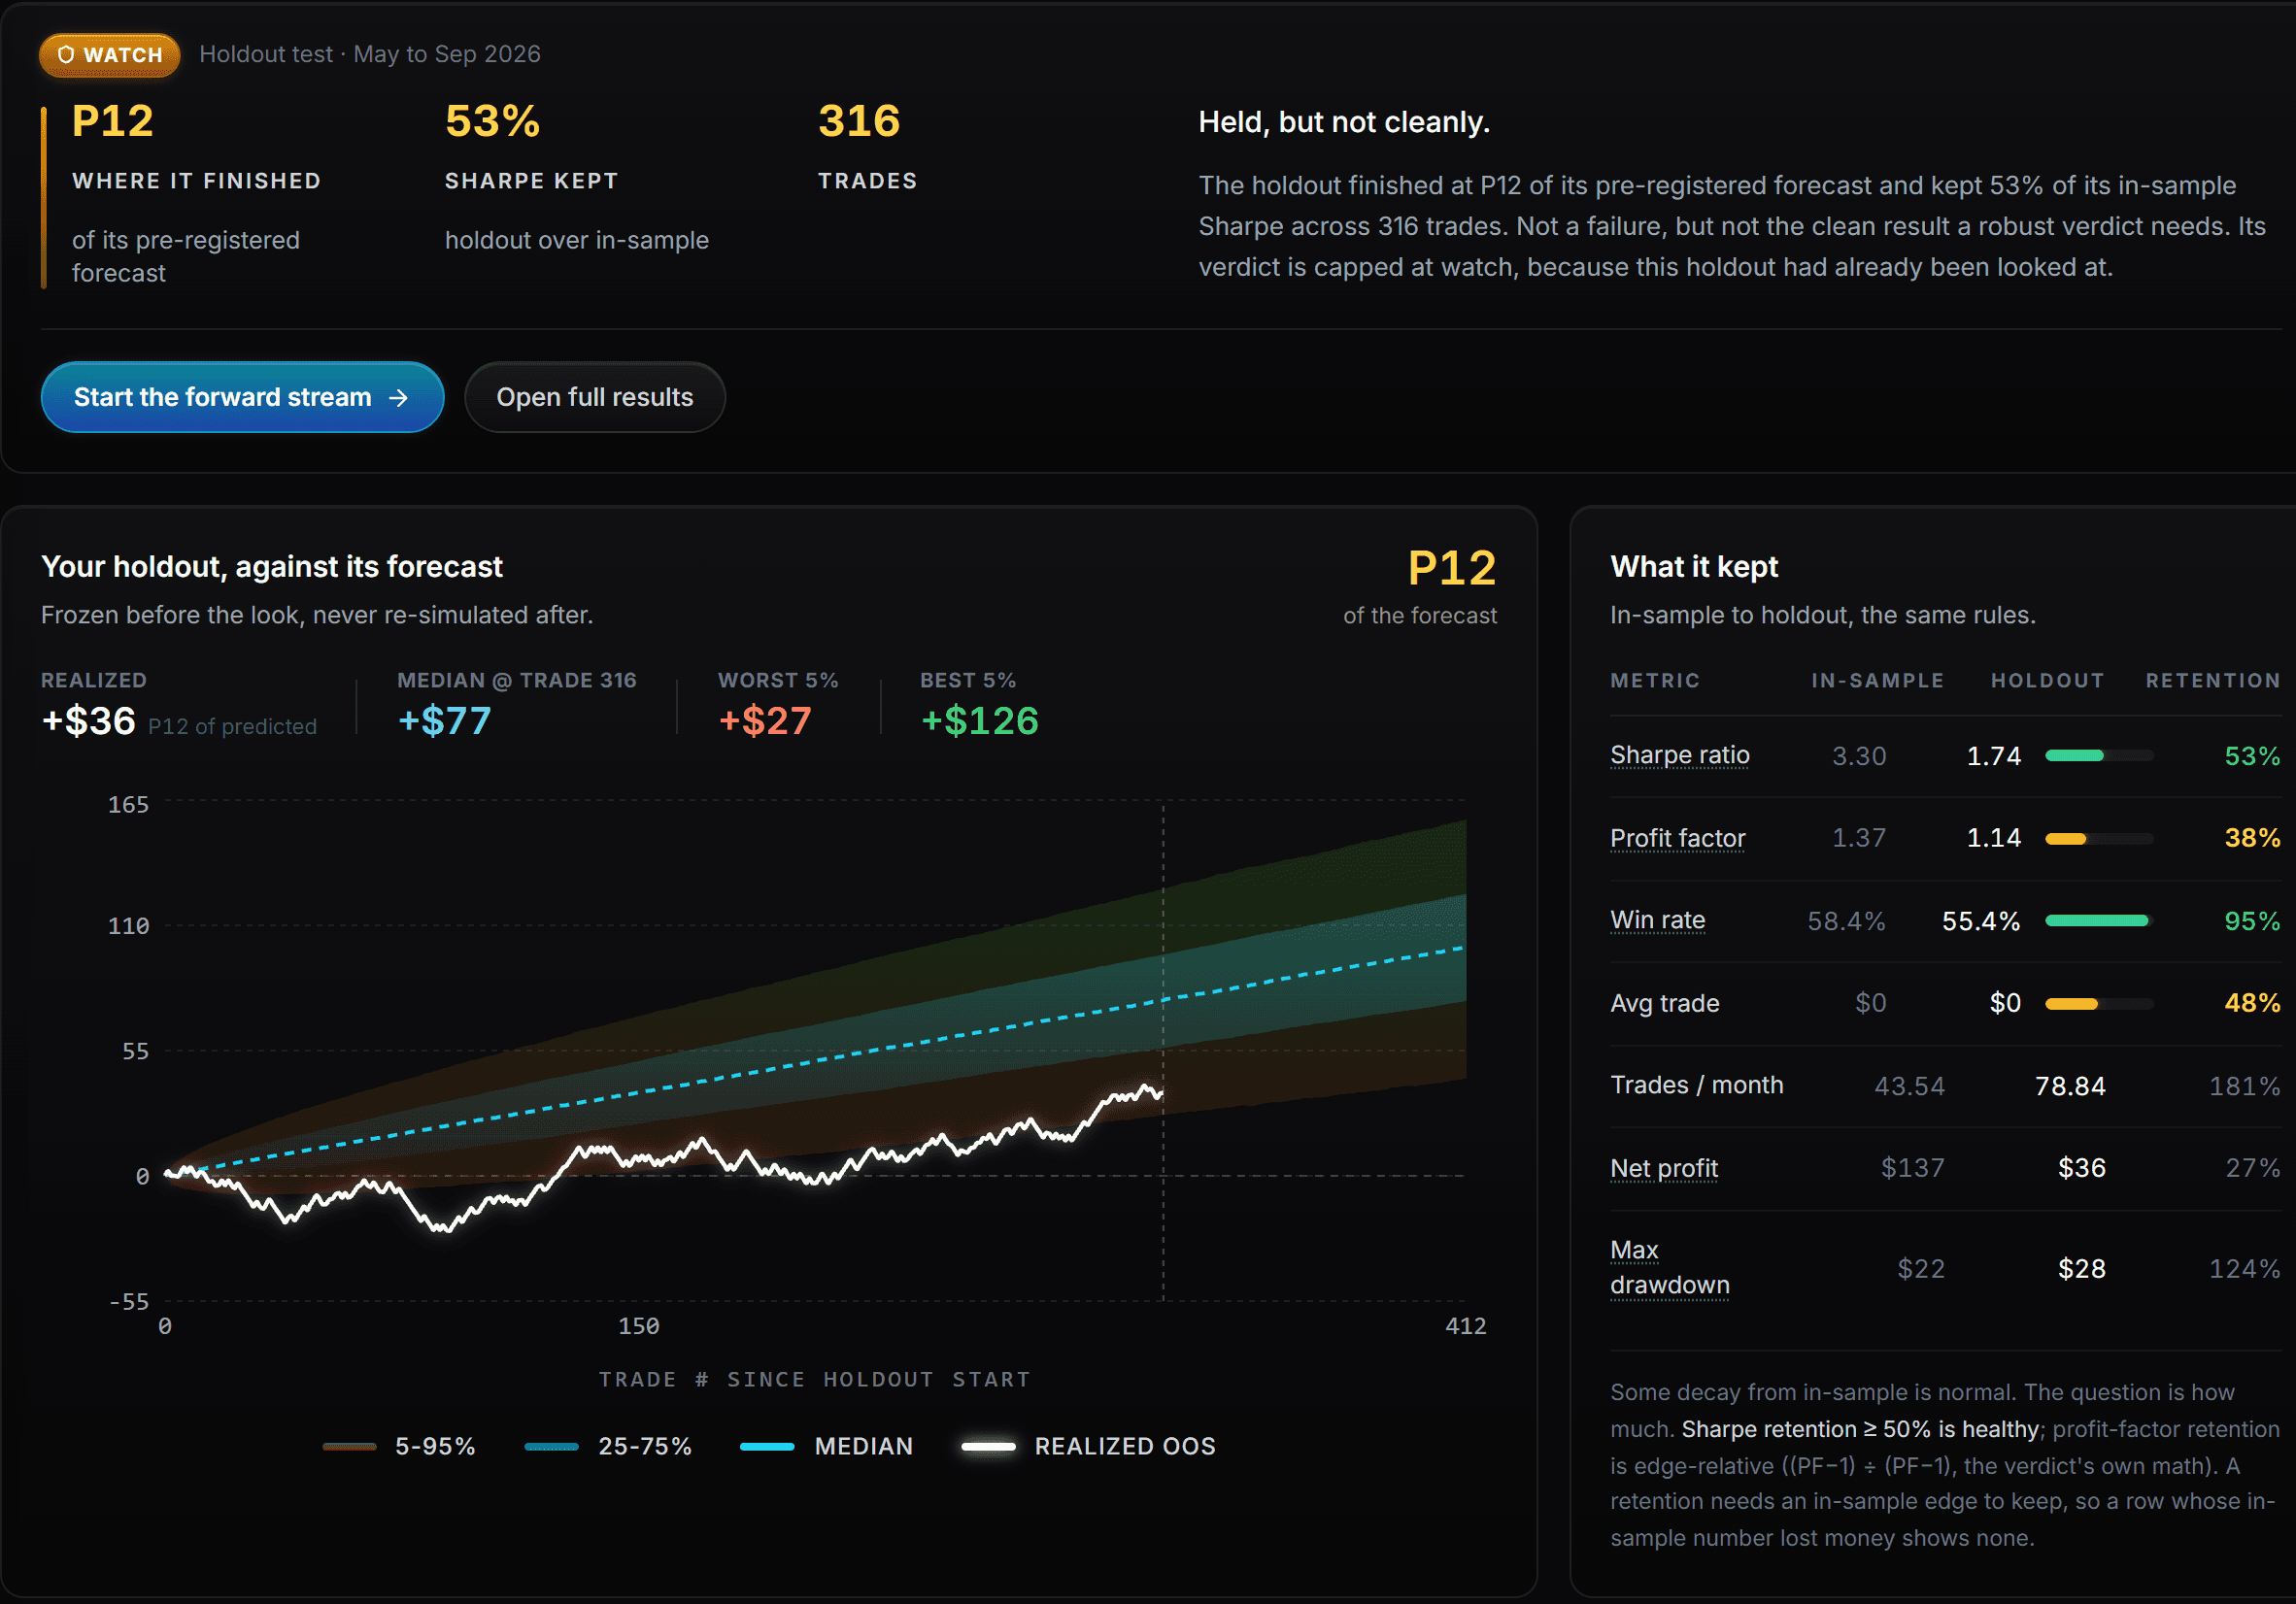
- Keep a stretch of history untouched while you research, then test the finished strategy on it one time. A look you can only take once can't be re-rolled.
One look, taken once.
Every project keeps its most recent months sealed from the start. When the strategy is ready, its champion is tested on them once; the project records anything that touched them before, so a clean result is known to be clean.
A holdout too short to tell good from bad is marked inconclusive before the look is spent, not after.
Simulated results. They have inherent limitations. Read the full statementHide the statement
These results are based on simulated or hypothetical performance results that have certain inherent limitations. Unlike the results shown in an actual performance record, these results do not represent actual trading. Also, because these trades have not actually been executed, these results may have under-or over-compensated for the impact, if any, of certain market factors, such as lack of liquidity. Simulated or hypothetical trading programs in general are also subject to the fact that they are designed with the benefit of hindsight. No representation is being made that any account will or is likely to achieve profits or losses similar to these being shown.
AlgoLift Desk
A desktop app that will run a strategy you validated here on your own broker or prop account, from your own computer. It is in development. Everything below describes the design, not a product you can use today.
- The engine your backtest ran
- The Desk is being built to run the same engine build your strategy was validated on, so live decisions follow the logic you tested.
- Your computer, your account
- Orders would go from your computer to your broker or prop platform. Your credentials would never reach AlgoLift, and neither would your orders.
- Your firm's rules, before every order
- Drawdown, daily loss and contract limits checked before an order leaves. Where a firm bans automation, the Desk would not send orders at all.
- You stay in charge
- Watch-only, one click per trade, or automatic where your firm allows it. Pausing or flattening would work from anywhere, including your phone.
- Measured against its twin
- Every live trade compared with what the engine expected on the same data, so you see what execution actually costs instead of guessing.
- Checked every night
- Each night the Desk's decisions would be replayed against our own history of the day. A decision that doesn't match gets flagged, not buried.
Forward and live, plainly.
No. Today AlgoLift builds, backtests and forward-tests strategies on real market data. Live execution is on AlgoLift's roadmap and not available yet. AlgoLift does not place trades, connect to brokers or send signals.
A backtest replays history your strategy may have been tuned on. A forward test runs on days that did not exist when you built it, and it is scored against a range saved before you deployed, so a good result can't be explained by hindsight.
No. The Desk is being designed to run on your own computer and send orders straight to your broker or prop platform. AlgoLift would never hold your broker credentials or sit between you and your orders.
It depends on the firm and the account phase, and the rules change often. Some firms allow automation, some require you to be present, and some ban it outright. Whatever platform you use, check your firm's current rules before automating anything.
There is no date yet. We will announce it when it is ready to use, not before, and we will not take payment for it until it exists.